

—Legislation paves way for up to $3 million in micro-credit financing for small businesses and entrepreneurs
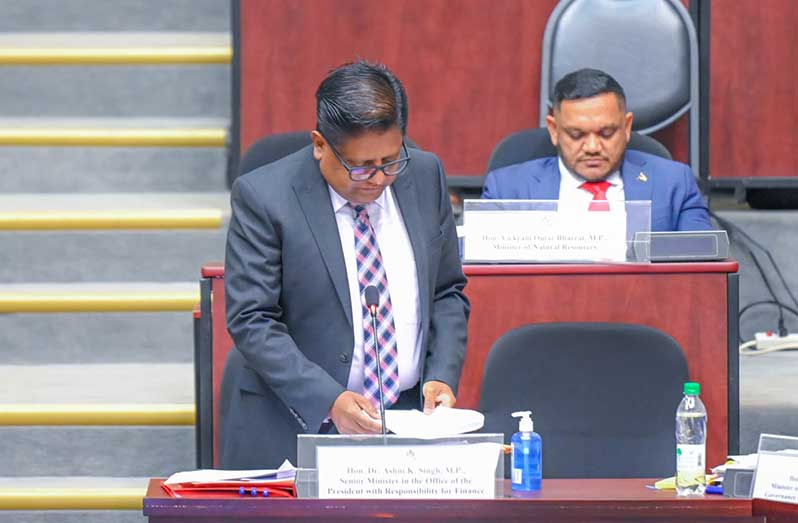
THE Government, on Friday, tabled the Guyana Development Bank Bill 2026 in the National Assembly, advancing plans to establish a dedicated financial institution aimed at expanding access to credit and supporting the growth of small and medium-sized enterprises (SMEs).
Senior Minister in the Office of the President with Responsibility for Finance, Dr Ashni Singh, tabled the proposed legislation which forms part of the government’s broader agenda to empower citizens and create greater opportunities for participation in the country’s expanding economy.
Under the bill, the Guyana Development Bank will provide SMEs and aspiring entrepreneurs with access to micro-credit loans of up to $3 million at a zero per cent interest rate. The programme will also pair financing with mentorship and training to help businesses grow and improve their chances of long-term success.
President Dr Irfaan Ali, while leading a Cabinet outreach in Region Seven earlier this week, reaffirmed that the bank is intended to support community-driven development by enabling residents to invest in small enterprises, form consortiums and pursue larger projects collectively.
The initiative fulfils a commitment outlined in the People’s Progressive Party/Civic (PPP/C) manifesto to foster a more inclusive financial system that allows more Guyanese to access financing, savings and investment opportunities.
“The Guyana Development Bank will allow us to target you directly, so that you can benefit from soft loans that will allow you to invest in small businesses, that will allow you to come together in a consortium and do larger projects,” President Ali said.
The development of Guyana’s financial sector remains a key component of the government’s strategy to ensure citizens benefit from the country’s economic transformation. Access to financing is viewed as a critical pillar for the establishment, growth and sustainability of businesses, while also supporting household and individual economic empowerment.
Under the stewardship of the PPP/C administration, Guyana’s financial sector has recorded significant improvements across several key indicators.
Between the end of 2020 and the end of 2025, total credit to the private sector grew by 104.7 per cent, driven by increased lending to the services, manufacturing, agriculture, mining and quarrying sectors. Lending for real estate mortgages also expanded significantly, increasing by 104.6 per cent over the same period.
Commercial bank deposits surged by 132.8 per cent by the end of 2025 compared with the end of 2020, reflecting rising incomes and growing confidence in the banking system.
Meanwhile, the ratio of non-performing loans declined from 10.8 per cent at the end of 2020 to 1.3 per cent by the end of 2025, supported by stronger economic activity following the pandemic and enhanced risk management practices within the financial sector.
These trends, the government noted, demonstrate the resilience of Guyana’s financial system and its growing role in supporting the country’s economic transformation.
The government said it remains committed to working with consumers, businesses and other stakeholders to strengthen the business environment and create opportunities for sustainable economic development.