

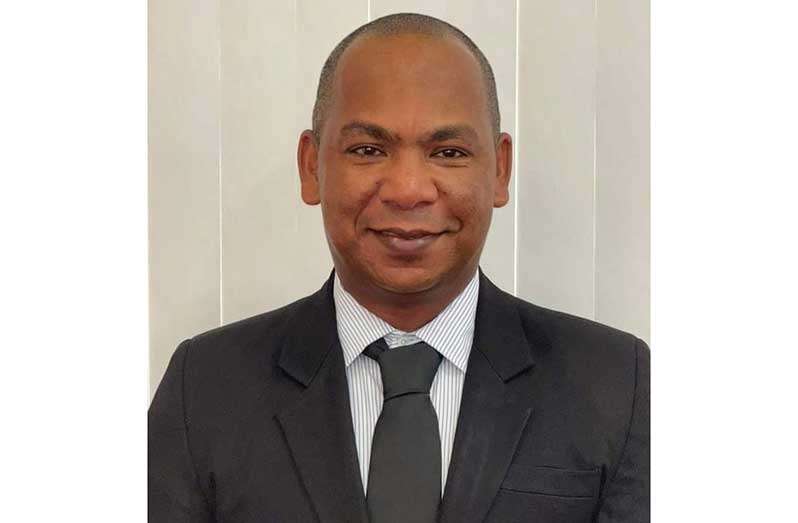
A COMPANY registered in the name of Adonika Alicia Aulder, the wife of former Assistant Commissioner of Police Calvin Brutus, received approximately $130 million in deposits over a seven-month period.
The sum at reference, according to the testimony of a financial analyst, includes $43.3 million linked to approved government payment vouchers.
Brutus, an attorney-at-law by profession, is facing one count of misconduct in public office, and 221 counts of liability of an official. The trial, which began in July, is being heard before Principal Magistrate Faith McGusty at the Georgetown Magistrates’ Courts.
Brutus served 25 years in the Guyana Police Force (GPF) before being dismissed on February 5, 2025, following a disciplinary tribunal inquiry into alleged financial misconduct.
He was subsequently charged by the Special Organised Crime Unit (SOCU) with a range of financial offences, including misconduct in public office, money laundering, obtaining money by false pretence, larceny by a public officer and liability of an official.
When the trial continued recently, financial analyst Ganesh Lachminarine took the witness stand and gave evidence about his examination of Triple A Depot’s records.
He told the court that 56 cheques, linked to 208 payment vouchers, were deposited into the company’s Republic Bank account.
Through Lachminarine’s testimony, SOCU prosecutor and attorney Darin Chan led evidence showing that Triple A Depot conducted business with the GPF. The transactions occurred while Brutus served as Acting Deputy Commissioner of Police (Administration).
Lachminarine said the vouchers had a combined value of $43,352,223, and that the transactions were approved. Asked about the company’s registration, the analyst testified that Triple A Depot was registered on June 21, 2023, in the name of Adonika Alder, Brutus’ wife.
He told the court that the business was registered to supply items, among them food boxes, pumps and hardware. Explaining the purpose of his financial analysis, Lachminarine said he sought to establish whether payments recorded in the Integrated Financial Management and Accounting System (IFMAS) vendor analysis report had been deposited into the company’s bank account.
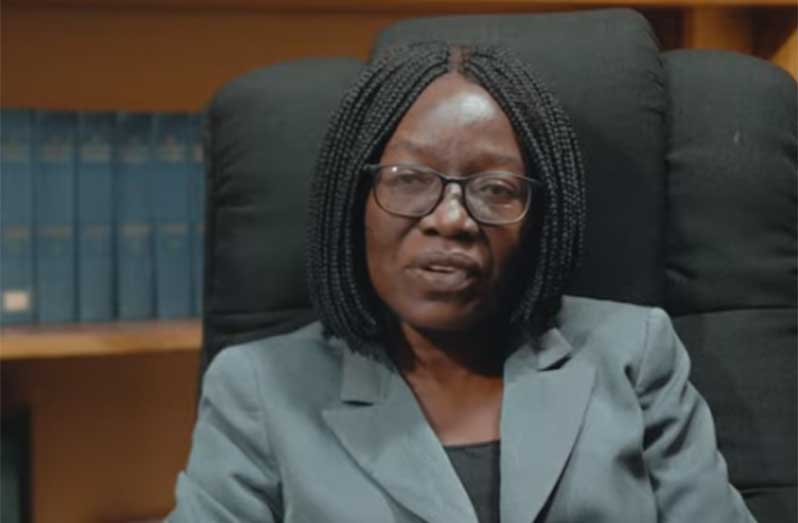
He also examined whether payments were made to suppliers.
“The methodology that I would have used was to compare the payments as per the IFMAS report,” he told the court, explaining that he compared those figures with the deposits reflected in Triple A Depot’s banking records.
Lachminarine said his review of the vendor analysis report identified 208 payment vouchers with a total value of $43,352,223.
He testified, “The finding that I would have observed [was] that out of the 208 vouchers, 56 cheques were deposited into the account.” The analyst further told the court that the account received approximately $130 million in deposits between January and July 2024.
Of that sum, approximately $43 million was linked to the payments reflected in the IFMAS vendor analysis report. Lachminarine said the account was opened on January 9, 2024, and that the records showed an initial cash deposit of $10,000 on that date, followed by a $20,000 deposit the next day.
He explained that he verified the payments by examining the deposit slips and checking the totals against the bank statements. “I would have checked, examined the deposit slips,” Lachminarine said, adding: “The total on the deposit slip was then verified to the bank statement.”
He confirmed that the figures corresponded with the amount recorded in the vendor analysis report. The witness also explained why the payments appeared as several separate deposits rather than one transaction.
He said that multiple cheques were recorded on separate deposit slips, with the bank recording the combined value of the cheques on each slip.
Lachminarine’s examination also identified a payment of $7.38 million made from Triple A Depot’s account to a supplier identified in February 2024. The analyst said his assessment was based on the company’s registration documents, deposit slips, bank statements, scanned copies of cheques, and the IFMAS report.
Brutus was represented by Attorneys-at-Law Yuborn Allicock and Domnick Bess. The trial continues on December 1.
In the ongoing proceedings, Brutus is facing one count of misconduct in public office and 221 counts of liability of official as part of a wider SOCU investigation into the alleged misappropriation of approximately $800 million in GPF funds.
It is alleged that Brutus, while serving as Assistant Commissioner of Police and performing the duties of Deputy Commissioner, Administration, used the authority of that office to create the opportunity for his wife, through businesses connected to her, to defraud the State of large sums of money.
This matter is one of several trials before the Magistrates’ Court arising out of a 2024 SOCU investigation into alleged financial irregularities within the GPF.
Prosecutors contend that while serving as Acting Deputy Commissioner of Police (Administration), Brutus diverted public funds for personal gain.
Approximately $300 million has been linked to properties and other assets owned by Brutus and his wife, while another $500 million remains frozen in bank accounts belonging to the couple, their businesses and their son.
Brutus, along with his wife, Adonika Aulder; Police Sergeant Kevin George; Latoya Brummell; and businessman Asif Zafarally, is facing multiple criminal charges, including money laundering, in connection with the alleged misappropriation of State funds.
Brutus remains on more than $16 million bail, while his co-accused have also posted substantial cash bail. As part of their bail conditions, they are required to lodge their passports with the authorities and report to the police periodically.
Brutus has previously denied the allegations, asserting that the money was derived from his personal savings, as well as cash gifts received for his wedding and during holidays.